UNITED STATES OF AMERICA —SSR Mining Inc. has entered into a definitive agreement to acquire all issued and outstanding shares of Roxmore Resources Inc. through a court-approved plan of arrangement. Under the terms of the transaction, Roxmore shareholders will receive C$6.75 per share in cash alongside common shares in a newly formed exploration spin-off entity. The fully diluted in-the-money equity value of the acquisition is estimated at approximately $464 million, with an enterprise value of $392 million, funded entirely from SSR Mining's existing cash reserves.
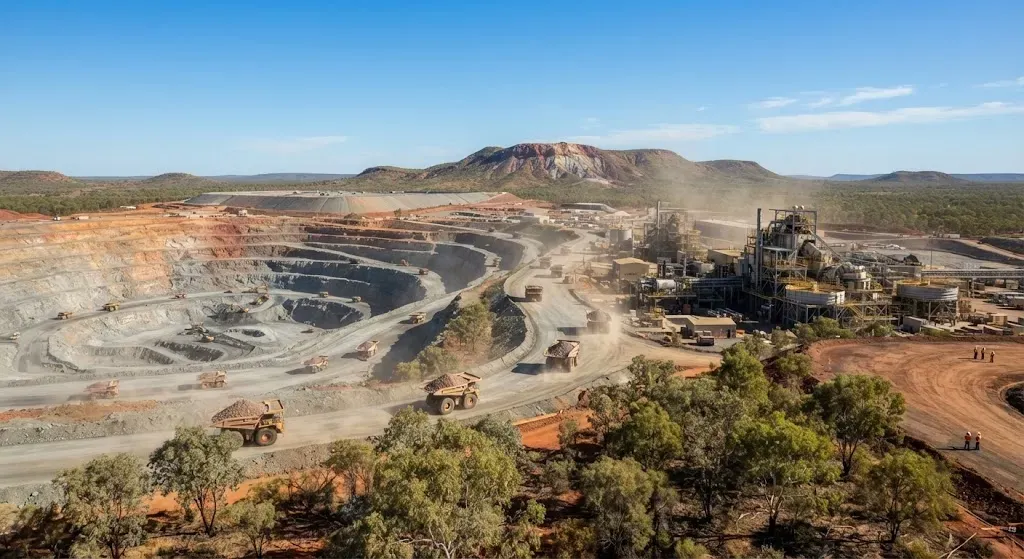
The acquisition brings Roxmore's Converse Gold Project-situated six kilometers from SSR Mining's Marigold Complex in Nevada-directly into the company's operational footprint. By developing Converse as a contiguous asset rather than a standalone operation, the company expects to unlock substantial efficiencies, eliminate duplicate corporate expenses, and optimize fleet management and water rights. Technical evaluations project life-of-mine synergies exceeding $200 million, alongside an estimated production addition of 150,000 to 170,000 ounces of gold annually over a decade-long mine life starting in the early 2030s.
The transaction strengthens the competitive positioning of major gold producers operating within tier-one North American mining jurisdictions. For the broader industry, the deal underscores a growing strategic emphasis on district-scale consolidation, where proximity to established processing infrastructure allows companies to lower capital intensity and de-risk major greenfield developments. By integrating contiguous multi-million ounce resources, established operators can defer heavy capital expenditures while enhancing long-term reserve replacement profiles.
For market participants and institutional investors, the all-cash structure preserves the acquirer's free cash flow leadership while avoiding equity dilution. The transaction is projected to be immediately accretive to net asset value and mineral resource metrics, delivering an internal rate of return exceeding corporate hurdle rates. With no material capital expenditures required until the early 2030s, the combined US platform is positioned to sustain production levels between 350,000 and 400,000 ounces annually through the decade.